Market overview and structural significance of the Spirometer Flow Sensor Market
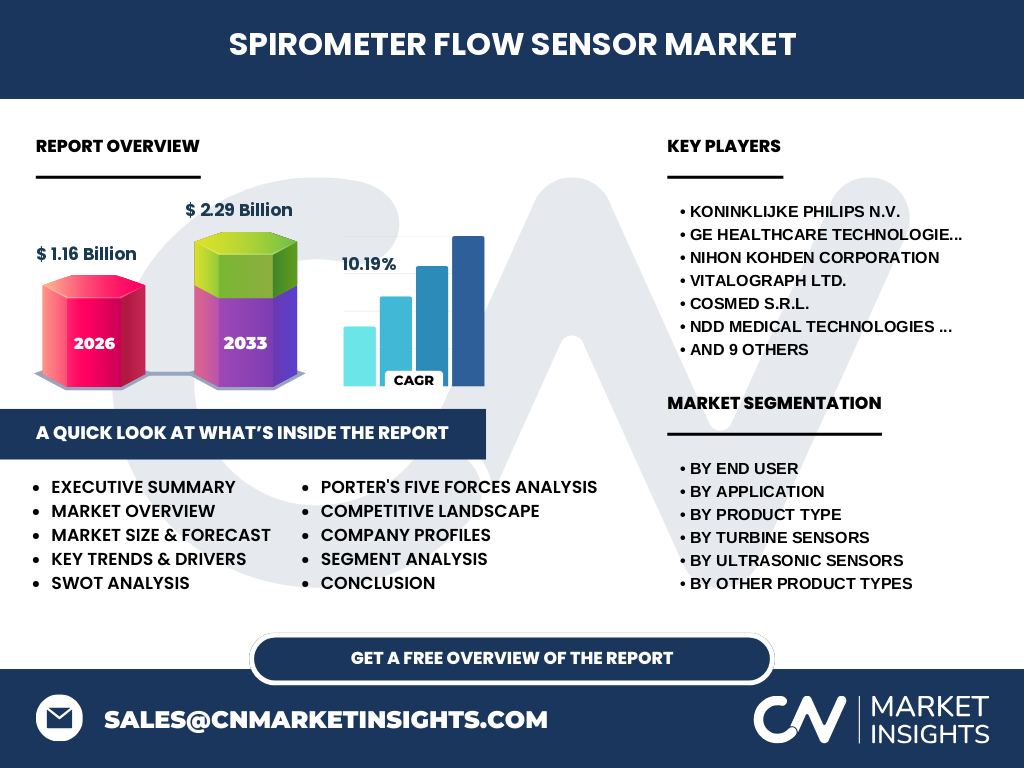
Our analysis indicates that the Spirometer Flow Sensor Market is valued at 1.16 Billion in 2026, driven by rising pulmonary chronic illnesses. These specialized transducers measure respiratory gas velocities using differential pressure, ultrasonic, and turbine mechanisms, forming the critical diagnostic core for airway management devices regulated by the FDA and EMA.
Structural Growth Drivers and Market Restraints
The market is accelerated by surging COPD prevalence and remote patient monitoring adoption, though high calibration costs and stringent ISO 26782 accuracy standards act as persistent restraints. Supply chain bottlenecks involving medical-grade silicones and piezoelectric crystals further challenge component procurement for manufacturers.
Emerging Industry Trends and Technological Shifts
The shift toward connected care is reshaping demand, favoring transceiver ultrasonic sensors that eliminate moving parts and reduce cross-contamination risks. Digital health integration allows continuous home telemetry, pushing established players to upgrade their disposable sensor portfolios for decentralized clinical settings.
Pandemic Impact and Post-COVID Recovery Dynamics
COVID-19 temporarily depressed elective pulmonary function tests due to aerosol generation risks, yet it permanently elevated awareness of respiratory health. The post-pandemic recovery trajectory shows robust double-digit expansion as hospitals replace aging spirometry fleets and expand outpatient diagnostic capacity.
Competitive Benchmarking and Industry Consolidation
Industry leadership is consolidated among innovators like Koninklijke Philips N.V. and GE HealthCare Technologies Inc., which leverage expansive hospital distribution networks. Meanwhile, specialized challengers like ndd Medical Technologies AG and COSMED S.r.l. compete through proprietary TrueFlow ultrasound and portable diagnostic architecture.
Executive Summary: Key Findings in the Spirometer Flow Sensor Market
Our research projects the market to surge from 1.16 Billion in 2026 to 2.29 Billion by 2033 at a CAGR of 10.19%. Growth is heavily concentrated in digital-first home healthcare and compact differential pressure transducers meeting stringent clinical accuracy mandates.
Long-Term Market Forecast from 2027 to 2033
Driven by an accelerated 10.19% CAGR, market valuations will climb steadily to reach 2.29 Billion by the end of 2033. This trajectory reflects compounding demand for recurring disposable sensor purchases and expanding municipal investments in respiratory screening programs.
Segmentation Breakdown: Products, Applications, and End Users
Segmentation spans Differential Pressure Sensors, Ultrasonic Sensors, and Turbine Sensors deployed across hospitals, diagnostic centers, and home care. Applications cover Forced Vital Capacity (FVC), Slow Vital Capacity (SVC), and Peak Expiratory Flow monitoring, with direct sales and online retail handling distribution.
Geographic Distribution and Regional Market Analysis
North America dominates consumption due to entrenched reimbursement frameworks and high chronic disease awareness, while Asia-Pacific represents the fastest-growing regional market. Localized manufacturing hubs in Western Europe also maintain strong export volumes complying with MDR requirements.
In-Depth Regional Review and Localized Constraints
North American growth is bolstered by centralized hospital procurement, whereas European markets navigate stringent CE-MDR compliance timelines. In contrast, Asia-Pacific expansion relies heavily on public health modernization initiatives and rising adoption of low-cost turbine sensors in regional clinics.
Strategic Positioning of Leading Company Profiles
Firms such as Vitalograph Ltd. and Medikro Oy focus on ultra-portable PC-based spirometers, while NuvoAir AB pioneers smartphone-linked digital therapeutics. Concurrently, legacy vendors like Nihon Kohden Corporation integrate robust multi-parameter clinical monitors with precision pneumotachograph flow heads.
Porter's Five Forces Competitive Assessment
Industry rivalry is intense, driven by continuous patent filings in ultrasonic transit-time measurement. Supplier power remains moderate due to specialized raw material requirements, whereas buyer power is mitigated by the critical need for FDA-cleared diagnostic precision.
SWOT Analysis of the Global Industry Ecosystem
Key strengths include high clinical precision and expanding digital integration, counterbalanced by strict regulatory approval hurdles. Opportunities abound in emerging home healthcare segments, while supply chain disruptions for specialty resins represent an ongoing external threat.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing medical-grade plastics, ceramics, and wires. Component manufacturers fabricate the sensing elements, which are integrated by OEMs like COSMED S.r.l. or Geratherm Respiratory GmbH before reaching hospitals via distributors and direct channels.
Strategic Investment Insights and High-Potential Areas
Investors should target developers of disposable ultrasonic flow tubes and connected home-monitoring platforms, as these segments capture high-margin recurring revenues. Capitalizing on partnerships with telehealth providers offers substantial growth leverage.
Conclusion and Strategic Takeaways
The Spirometer Flow Sensor Market represents a high-growth medical technology sector set to reach 2.29 Billion by 2033. Success depends on navigating regulatory landscapes and pivoting toward digital, maintenance-free sensor technologies.
Research Methodology and Baseline Data Triangulation
Our baseline estimates are triangulated by combining customs trade registry data, primary executive interviews with key opinion leaders across ndd Medical Technologies AG and Vitalograph Ltd., and secondary macroeconomic health expenditure indicators from global pulmonary societies.
Scope of the Report and Coverage Parameters
This report evaluates the global industry across product categories, applications, and distribution channels from 2026 to 2033. Limitations include restricted data transparency in private direct-to-consumer digital health startups and localized medical device pricing discrepancies.
Recent Industry Developments and Strategic Moves
Recent milestones feature NuvoAir AB securing expanded payer coverage for decentralized respiratory trials and Medical International Research S.p.A. launching next-generation turbine flow meters with Bluetooth connectivity. These moves signal an industry-wide pivot toward software-enabled diagnostic mobility.